May 2016
TS-177-ITAT-2016(Mumbai ITAT) Capegemini S.A. A.Y.: 2009-10, Date of Order: 28th March, 2016
fiogf49gjkf0d
Article 23 of India- France DTAA – Guarantee commission paid pursuant to a corporate guarantee agreement executed in France between a French Company and a French Bank, does not arise in India – Such commission is not taxable in India under the ‘other income’ article of the DTAA
Facts
The Taxpayer, a French Company provided a corporate guarantee to a French bank (bank). In lieu of such guarantee, the Indian branch of the bank provided loan to the Indian subsidiaries (ICo) of Taxpayer. ICo paid guarantee commission to the Taxpayer towards the guarantee given to the bank. The AO contended that the guarantee commission paid to the taxpayer arises in India and therefore, was taxable under “Other income” Article 23 of the India-France DTAA , for the following reasons
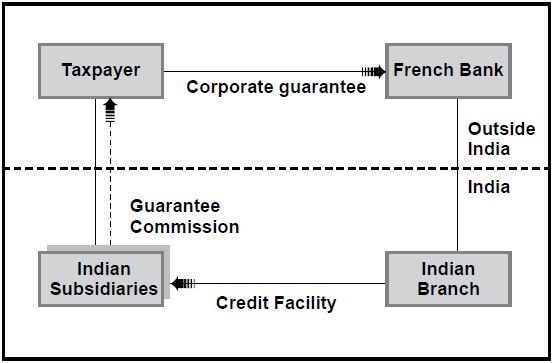
The guarantee had been provided for the purpose of raising finance by an Indian company
Finance was raised in India and the benefits were availed by Indian subsidiaries
Finance requirement was met by Indian branch of the French bank.
The Taxpayer, however, contended that guarantee commission did not arise in India and accordingly was not taxable in India.
Held
On appeal, ITAT held:
Guarantee commission received by the taxpayer does not accrue or arise in India, nor is it deemed to accrue or arise in India and therefore, it is not taxable in India under the Act.
Guarantee was given by a French company to a French bank in France. Therefore, such guarantee commission arises in France and not in India. Therefore, guarantee commission paid to the Taxpayer is not taxable in India under Article 23(3) of the DTAA .














